The Transatlantic Accountability Squeeze on American Gas
The U.S. Gulf Coast LNG industry expanded rapidly after 2022 as European buyers turned to American cargoes to replace disrupted pipeline supplies and reinforce energy security. That commercial relationship created a powerful new link between U.S. upstream operations, coastal liquefaction terminals, European import policy, and the credibility of emissions data attached to each shipment. Cheniere, one of the largest U.S. LNG exporters, has reported that approximately 75% of its LNG volumes produced since the beginning of 2022 were delivered to Europe, illustrating how closely American export economics became tied to the European market.
The next phase will be defined less by liquefaction capacity than by evidence. The European Union”s Methane Regulation is moving importers toward measurement, monitoring, reporting, and verification requirements that reach beyond EU borders. The central conflict is straightforward: historical inventories often rely on emission factors and engineering assumptions, while the emerging regime increasingly expects physical measurements that can identify, quantify, and reconcile methane releases at specific assets. For U.S. producers and Permian Basin suppliers, a spreadsheet estimate will no longer carry the same commercial weight as a defensible record built from sensors, inspections, and satellite observations.
Regulatory Convergence Under the EU Methane Regulation Framework
The EU Methane Regulation establishes obligations across the oil, gas, and coal sectors, with consequences for non-EU producers that sell into the European market. Importers must provide information under Annex IX, while supply-chain participants face growing expectations around emissions quantification, leak detection and repair, and restrictions on venting and flaring. The framework is not limited to the LNG terminal receiving a cargo. It reaches backward through production, gathering, processing, transmission, liquefaction, and shipping data.
The implementation path is staged, but the direction is clear. The framework has moved from generic-factor quantification toward direct measurement, with source-level quantification for non-operated assets and annual site-level measurements expected to become increasingly important. The broader methane-intensity standards are expected later in the decade, but commercial decisions are already being affected because buyers, banks, and portfolio managers cannot wait for every technical detail to be finalized before assessing exposure.
- Importers must assemble emissions information for fossil fuels produced outside the EU.
- Operators are expected to strengthen measurement, monitoring, reporting, and verification systems.
- Independent third-party verification is central to the credibility of annual reports.
- Member states may impose significant penalties, potentially reaching up to 20% of prior-year revenue under the framework described by industry analyses.
- Third countries may seek recognition of equivalent monitoring systems, although equivalence criteria and implementation details remain consequential uncertainties.
For U.S. LNG, the commercial risk is a potential split between cargoes that can demonstrate a verified methane profile and cargoes supported mainly by modeled averages. European buyers may not immediately reject unverified supply, but uncertainty can translate into additional screening, tighter contractual warranties, lower premiums, or greater reliance on alternative sources. Independent peer-reviewed assessments of satellite flaring and emissions sensing have also highlighted the persistent gap between modeled inventories and empirical observations. The monitoring literature available through the peer-reviewed sensing research underscores why no single measurement layer can be treated as universally sufficient.
Ground Truth Versus Overhead Reality Across the LNG Value Chain
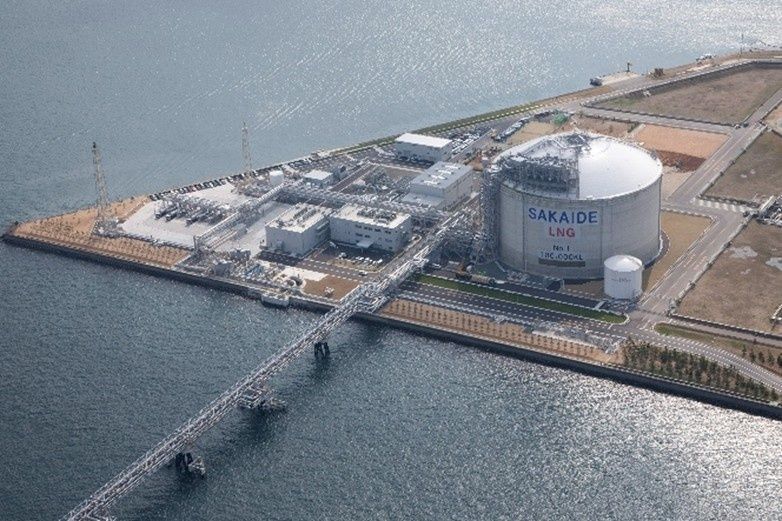
The emerging compliance architecture is inherently multi-layered. At Gulf Coast liquefaction hubs, terminal operators can combine acoustic sensors, optical gas imaging, handheld surveys, fixed fence-line monitors, and process instrumentation. These tools answer different questions. Acoustic systems can help identify the sound signature of pressurized releases, optical gas imaging can visualize methane escaping from equipment, and continuous monitors can establish time-series data around sensitive areas. Together, they offer a ground-level view of compressors, valves, storage equipment, loading systems, and other potential sources.
Satellite systems provide a different form of evidence. High-resolution orbital constellations can scan broad producing regions and identify large, unannounced plumes from well pads, gathering infrastructure, processing facilities, and compressor stations. Their principal advantage is geographic reach, particularly across the Permian Basin, where ownership is fragmented and supply may pass through multiple operated and non-operated assets before reaching a Gulf Coast terminal. Their limitation is equally important: satellites do not observe every release, especially short-duration, obscured, or below-threshold events. The strongest compliance case therefore comes from reconciling satellite alerts with aircraft, drone, mobile, and ground-based investigations.
| Monitoring layer | Primary strength | Principal limitation |
|---|---|---|
| Fixed acoustic and fence-line sensors | Continuous local monitoring and rapid event detection | Limited geographic coverage and potential interference from surrounding operations |
| Optical gas imaging | Visual confirmation of leaks at specific equipment | Often periodic rather than continuous, with performance affected by weather and operating conditions |
| Aircraft and drone surveys | Flexible coverage with useful source-level confirmation | Requires scheduling, skilled interpretation, and repeat surveys |
| High-resolution satellites | Wide-area screening and detection of major plumes | Thresholds, revisit intervals, cloud cover, and short-lived events can limit detection |
| Engineering factors and desktop models | Scalable reporting across large asset portfolios | May miss site-specific super-emitters and operational variability |
This distinction matters because methane emissions are unevenly distributed. A small number of high-emitting events can materially change the footprint of an otherwise efficient supply chain, yet those events may disappear inside an average emission factor. Satellite observations can expose that problem at the basin level, while terminal monitoring can verify the integrity of the final processing and loading stages. The resulting dataset is more demanding to manage, but it is also more defensible when buyers, regulators, or financiers challenge a cargo”s environmental claims.
Overhauling EPA Reporting and Domestic Baseline Compliance
U.S. reporting rules are moving in the same general direction, although they do not automatically produce a dataset that satisfies European requirements. EPA”s GHGRP Subpart W covers petroleum and natural gas systems, including emissions from equipment leaks, venting, flares, and combustion sources. Facilities generally fall within the program when they meet the applicable reporting threshold, commonly associated with 25,000 metric tons of carbon dioxide equivalent annually. Subpart W allows engineering calculations, direct measurement, emission factors, and approved leak-detection approaches, meaning operators may still need to reconcile several methodologies within one inventory.
The Inflation Reduction Act created additional authorities and financial mechanisms intended to reduce methane emissions. EPA”s 2024 rule strengthened and expanded reporting requirements, while subsequent rulemaking and legal developments have continued to shape the domestic baseline. The relationship between U.S. reporting and EU MRV expectations is therefore not automatic. A facility may be compliant with a domestic filing while still lacking the source-level measurements, independent verification, chain-of-custody controls, or non-operated asset data required by a European buyer.
EPA describes the reporting architecture and recent developments through its Methane Emissions Reduction Program and GHGRP Subpart W guidance. The practical message for operators is that empirical data are becoming more valuable even where engineering estimates remain legally available.
- Wellhead and compressor-station inventories must increasingly account for actual equipment condition and operating behavior.
- Subpart W records need stronger reconciliation with LDAR programs, maintenance logs, and third-party measurements.
- Non-operated joint ventures create data gaps that cannot be solved solely by improving the operator”s own facilities.
- Domestic reporting, methane charges, and European market-access documentation should be managed as connected financial exposures.
The economic stakes are not limited to regulatory paperwork. The Waste Emissions Charge has faced major legal and policy changes, including congressional disapproval of the 2024 final rule as described in EPA materials. Even when a particular charge is uncertain, the broader investment signal remains active: methane waste can create direct costs, remediation liabilities, reputational damage, and market-access friction. Producers that treat measurement as an accounting exercise may find that the cost of late remediation is higher than the cost of continuous monitoring deployed earlier.
Operational Transformation Across Upstream Basins and Coastal Terminals
Major liquefaction developers are responding by building certification and surveillance into commercial operations rather than treating them as separate environmental projects. Cheniere has described a climate strategy linked to enterprise risk assessment, scenario analysis, board oversight, and financial planning. Its corporate reporting has also referenced peer-reviewed life-cycle assessment work, supplier and academic collaboration on quantitative monitoring, and cargo emissions tags. These initiatives point toward a system in which the emissions profile travels with the gas and is updated as new measurements become available.
The hardest challenge is upstream transparency. LNG exporters may control the coastal terminal but depend on gas supplied through gathering networks, processing plants, pipelines, and joint ventures in Texas and New Mexico. Some assets are operated by third parties, and some suppliers may lack compatible monitoring systems. Commercial contracts will therefore need to address data standards, audit rights, remediation timelines, indemnities, and the consequences of an emissions event that affects a cargo after nomination but before delivery.
- Map every upstream source contributing gas to each export portfolio, including non-operated assets and commingled systems.
- Establish a measurement hierarchy that combines continuous local monitoring, periodic optical surveys, aerial campaigns, and satellite screening.
- Reconcile detected events with maintenance records, production volumes, flaring data, and regulatory reports.
- Attach digitally traceable emissions certificates or cargo emissions tags to spot and long-term transactions.
- Build contractual remedies for missing data, failed verification, unresolved leaks, and changes in methane intensity.
This transformation will alter procurement as well as operations. Buyers may increasingly request portfolio-level methane intensity, source-specific evidence, and verified updates rather than accepting a static annual certificate. Sellers with reliable digital records could gain better access to premium markets, while suppliers unable to document their performance may face discounts or exclusion from certain tenders. The result is a new form of gas differentiation based not only on molecule quality and delivery flexibility, but also on the credibility of the emissions record.
Navigating the New Standard of Transatlantic Gas Integrity
The central change in the transatlantic gas market is the replacement of paper assurance with empirical reconciliation. Emission factors and desktop inventories remain useful for establishing a baseline, but they cannot by themselves explain a major plume, a recurring compressor leak, or a short-lived release detected by an independent monitoring system. European import rules are pushing exporters to show how reported numbers were produced, which instruments were used, how gaps were handled, and whether the final result was independently verified.
That creates a strategic divide. Proactive exporters are assembling multi-tiered surveillance systems that connect wellheads, gathering networks, compressor stations, liquefaction plants, and cargo documentation. Laggards face more than possible penalties. They risk slower approvals, weaker negotiating positions, higher insurance and financing scrutiny, and reduced liquidity in a market where buyers increasingly compare carbon and methane intensity alongside price and destination flexibility. Verifiable low-carbon intensity will not replace security of supply as a priority, but it is becoming part of supply security”s definition. In the next stage of global gas trade, the most valuable cargo may be the one whose environmental integrity can be demonstrated from the field to the vessel.